The Discontinuity Illusion in Quantitative Screening
When researchers configure quantitative filters, intuitive thinking suggests that adjusting a threshold marginally will merely shave off borderline names. Setting an RSI cutoff at 70 produces one population; pushing that line to 72 might feel like a minor calibration. In real market distributions, however, values do not sit along a smooth Gaussian slope. They pool densely around popular momentum boundaries, consolidation bands, and historical benchmarks.
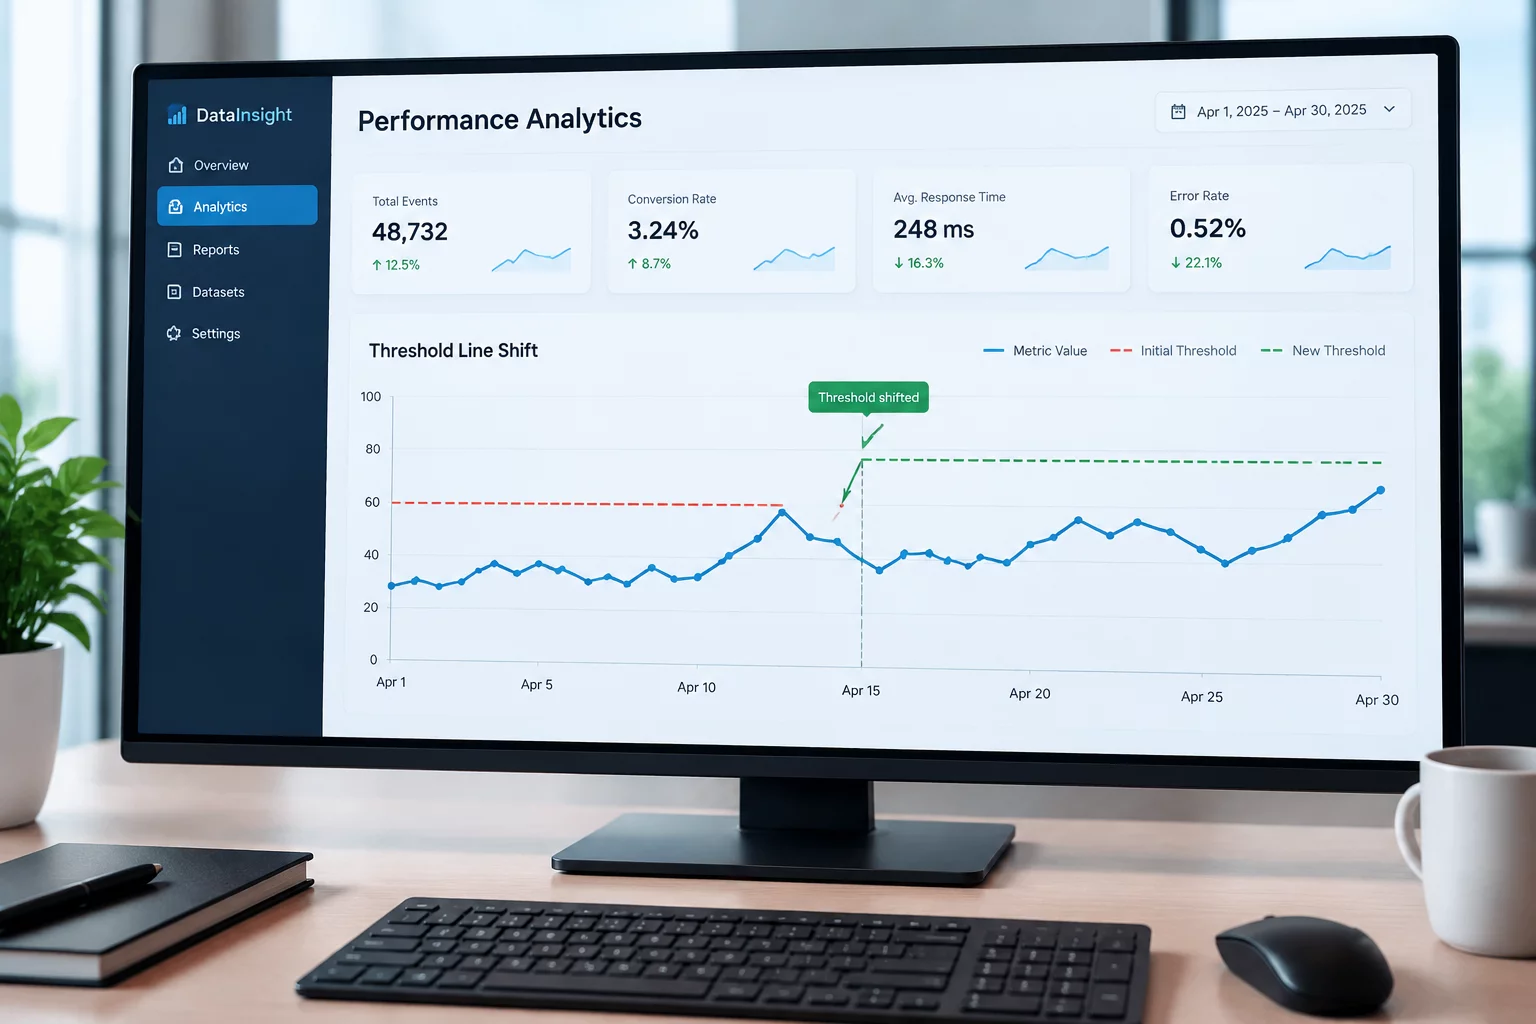
Crossing that exact mark exposed a steep cliff. Instead of losing the expected five or ten percent of marginal candidates, the resulting scan dropped nearly four-fifths of all qualifying stocks — from 42 survivors down to just 9. What seemed like a subtle quality adjustment operated as an aggressive structural sieve. The underlying research question had not changed, yet the resulting cohort represented an entirely distinct market regime.
Dissecting the 2-Point Variance and Population Collapse
A granular audit reveals why this collapse occurs. In a universe of 3,200 liquid symbols, momentum metrics cluster aggressively during market expansion cycles. Before the adjustment, dozens of consolidating leaders qualified alongside accelerating breakout names. Tightening the boundary severed the entire consolidation group, leaving only hyper-extended high-beta securities.
Furthermore, survivorship within the set skewed violently toward specific sectors. Technology and semiconductor names accounted for 32% of the pool at threshold 70, but surged to over 73% of the survivors at threshold 72. By tightening one metric without normalization across sector distributions, the scan secretly transformed from a broad strength screen into an undiversified momentum bet.
Downstream Implications for Empirical Research
Analysts evaluating backtests often mistake the superior backtested returns of the tighter threshold for enhanced predictive power. In reality, the tighter filter simply selected a concentrated tech basket during a strong semiconductor cycle. When market leadership rotated three weeks later, the tight-threshold cohort suffered drawdowns twice as steep as the baseline set. The threshold did not isolate higher quality; it merely isolated cyclical concentration.
Essential Screening Guardrails
- Run threshold elasticity curves across increments of 1% to identify hidden cliffs before committing to arbitrary cutoff numbers.
- Track sector and market cap distributions before and after every boundary change to detect accidental portfolio drift.
- Prefer percentiles within industry cohorts over absolute global thresholds when dealing with non-uniform distributions.